The best realtor for a first-time buyer is a licensed agent who represents buyers regularly, knows the towns you are shopping in, explains every step in plain language and puts compensation in writing before you tour a home. You can find that person by interviewing at least two or three agents, checking their license and asking past clients how they handled a stressful moment. This guide walks through what a buyer’s agent does, how to compare candidates, what to ask, how agents are paid and what to check before you sign.
TL;DR
- A buyer’s agent finds and shows homes, advises on price, writes and negotiates your offer and tracks deadlines through closing.
- Since the August 2024 industry changes, you generally sign a written buyer agreement before touring a home, and every term in it is negotiable.
- Interview several agents. Ask about experience with first-time buyers, local knowledge, communication hours, compensation and how to end the agreement.
- Check the agent’s license and any discipline with your state licensing agency, and call references.
- Get pre-approved and line up your inspector, title provider and insurance with your agent’s input, not after you have found a house.
Table of Contents
- What a realtor actually does for a first-time buyer
- Do you need a realtor at all?
- When to contact an agent
- How to find and compare candidates
- Questions to ask in the interview
- The buyer representation agreement
- How a buyer’s agent is paid
- Perspective: what we tell first-time buyers
- Work with a Maine agent who teaches as he goes
- Red flags when choosing an agent
- FAQ
- Sources
What a realtor actually does for a first-time buyer
First-time buyers often picture an agent as a person with a key to the lockbox. The real work is mostly invisible. Connecticut’s Department of Consumer Protection lists the tasks of a buyer’s agent: arranging showings, providing property and community information, disclosing known material facts, preparing market analysis, counseling on price, helping write and negotiate offers, keeping your objectives confidential, assisting with loan applications, monitoring deadlines and attending closing.
California’s Department of Real Estate describes the same job in its own terms. An agent should locate and show homes that match your needs and price range, help negotiate the purchase, explain disclosures and paperwork and give you copies of the purchase agreement and other documents. State rules differ, but the core duties are consistent.
For a first-timer, three of those tasks matter most.
Pricing and comparable sales
You have never watched a sale from the inside. A good agent pulls recent comparable sales, tells you whether a list price is realistic and helps you decide how far to go. In a competitive town that judgment can be the difference between a winning offer and an overpayment. If you are shopping Maine, our look at how multiple offers work in Maine shows what that conversation sounds like.
Contracts and contingencies
A purchase contract has deadlines for inspections, financing and disclosures. Miss one and you can lose leverage or your deposit. Your agent tracks those dates and tells you what each one means before you sign. In Maine, for example, the timing of seller disclosures can open a short window to back out, which we cover in our guide to mapping Maine disclosures to Title 33.
Your team
Agents see the same inspectors, lenders, title companies and attorneys every week and know who answers the phone. NAR suggests asking prospective agents whether they can refer you to mortgage, repair and closing providers. You are never required to use the first name you are given, but a short vetted list saves a week of cold calls.
Do you need a realtor at all?
No law says a buyer must use an agent, and some experienced buyers skip one. As a first-timer, you would be taking on the tasks above yourself: researching values, drafting or having an attorney draft the offer, tracking contingency deadlines, coordinating the inspection and handling the closing. You would also be negotiating directly with a seller’s agent whose job is to get the seller the best result.
The practical question is not whether you can, but whether you want to learn those skills while spending the largest amount of money of your life. If you choose to go without, hire a real estate attorney or a reputable title company to handle the contract and closing. Our comparison of how to vet a title company or attorney lists the questions that matter.
Most first-time buyers are better served by a good agent, because that agent’s incentive is to see the deal closed correctly and to protect your interests along the way. The rest of this guide is about finding a good one.
When to contact an agent
Talk to an agent before you start touring open houses. The order that works best for most first-time buyers:
- Check your credit and budget. Know your monthly comfort number, not just the maximum a lender will approve.
- Get pre-approved. A pre-approval letter tells sellers you are serious and tells you what you can afford. If you are unsure about loan types, ask an agent who works with FHA and conventional loans regularly to explain how they differ for your situation.
- Interview agents. Do this before you fall in love with a house, so you are choosing, not rushing.
- Sign a buyer agreement. You will generally need one before touring homes with an agent.
- Start touring. Now showings are productive, because you have a budget, a priority list and a person on your side.
If you are earlier in the process, a conversation six months out is still worthwhile. A good agent will tell you what to fix first, whether that is a down payment, a debt balance or a timeline.
How to find and compare candidates
The Consumer Financial Protection Bureau says buyers can find agents through referrals or real estate websites, and reminds them that many of those websites earn advertising revenue from agents. Treat a website’s ranking as an ad, not a review.
California’s Department of Real Estate recommends asking trusted people for recommendations, verifying the license, interviewing more than one agent, requesting past-client references, asking for proof of any specialization and choosing someone familiar with the area where you want to buy.
What to look for
The CFPB advises choosing an agent with experience in your preferred neighborhoods, price range and home type. That sounds obvious, but it eliminates a lot of candidates. An agent who mostly sells luxury waterfront homes may not be the best fit for a $280,000 starter house inland, and the reverse is true too.
For a first-time buyer, add four practical filters:
- Experience with buyers like you. Ask how many first-time buyers they have closed with in the past year, and what went wrong on the hardest one.
- Local depth. Can they speak to school districts, commute times, flood zones, property taxes, wells and septic systems in your target towns? In Maine, a question like well versus public water can swing your costs by thousands of dollars.
- Communication. Find out their working hours and how fast they reply. A buyer’s best listing alert is worthless if the agent answers on Monday.
- Teaching style. You should leave the interview understanding more than when you walked in.
Check the credentials
The CFPB recommends asking prospective agents for references and checking your state licensing agency for disciplinary actions. Most states let you search a license number online in a minute or two. A license tells you the agent met the state’s requirements. The REALTOR® designation additionally means membership in the National Association of Realtors and adherence to its Code of Ethics, which is why NAR’s own list suggests asking whether the agent is a REALTOR®.
Questions to ask in the interview
Use the same list with every candidate so you can compare answers side by side. NAR’s consumer guide suggests asking about the agent’s services, knowledge of your search markets, experience with buyers in your situation, scouting methods, agreement terms and compensation, provider referrals and references.
Fannie Mae adds that you should speak with several agents rather than feeling obligated to choose the first one, and suggests comparing expertise, career background, process, availability, references, contracts and costs. Its checklist also covers whether the agent mainly represents buyers or sellers, how many clients they handle at once, whether they work full time, what hours you can reach them, whether a contract is required and whether you can cancel.
Condensed into a form you can bring to the meeting:
| Topic | Question to ask | What a good answer sounds like |
|---|---|---|
| Focus | Do you mostly work with buyers or sellers? | Regularly represents buyers, with recent examples |
| Fit | How many first-time buyers have you helped recently? | A specific number and a story, not a general claim |
| Area | What should I know about the towns I’m considering? | Details on taxes, water and septic, flood risk and commute |
| Search | How will you find homes before they hit the portals? | A real process: alerts, agent network, tours |
| Availability | When can I reach you and how fast do you reply? | Clear hours and a realistic response time |
| Money | How are you paid and who pays? | A clear number or percentage in writing |
| Exit | Can I end the agreement if it isn’t working? | Yes, with defined terms |
| Proof | May I call past clients? | Names offered readily |
Pay attention to how the agent responds to a question about the downside of a house or a market. Someone who only tells you to buy now is not advising you.
The buyer representation agreement
This is the part that surprises most first-time buyers. HUD’s 2024 housing-counseling report says the practice changes tied to the NAR settlement became effective August 17, 2024, and that a buyer and agent must enter a written buyer agreement before visiting a property. The same report says all terms are negotiable, and that there is no national standard agreement, service package, commission charge or agreement length. State-specific rules cause agreements to vary.
NAR’s guide to written buyer agreements says the document outlines the agent’s services and compensation. Before signing, check these things:
- Compensation is clearly defined, for example $0, a flat fee, a percentage or an hourly rate, rather than open-ended or a range.
- You are signing terms you actually negotiated.
- You understand the services, the length of the agreement and the conditions for leaving it.
The CFPB suggests asking whom the agent represents, whether your conversations are confidential, how the agent is compensated and what happens if the brokerage also represents the seller.
Understanding what a buyer’s agent owes you
Connecticut’s consumer agency says a buyer’s agent owes the buyer fiduciary duties including loyalty, obedience, diligence, disclosure, confidentiality, accounting and reasonable skill and care. Duties can vary by state, so ask your agent to explain them in writing for yours.
NAR separates single agency, dual agency, subagency and designated agency. Dual agency, where one agent represents both sides, is allowed only in some states, and NAR says it can create conflicts and generally requires informed consent from both parties. If an agent raises it, ask how they would protect your price negotiating position.
A first-time buyer also has to line up services that are not part of the agent’s job. You will need homeowners insurance by closing, and understanding the insurance broker versus agent difference helps you shop for it sensibly.
How a buyer’s agent is paid
Compensation is negotiable. NAR says it may be a flat fee, a percentage or an hourly fee, and that the seller may pay it if you request that in your offer, or seller concessions may sometimes fund it. The written buyer agreement states the agreed amount. California’s Department of Real Estate notes that in a traditional deal most agents are paid a commission from the seller’s proceeds.
Two practical points for you:
- Ask what happens if the seller does not pay. If the agreement says you owe the difference, know the number before you tour.
- Be careful with side arrangements. Federal rules under RESPA generally prohibit paying anything of value for referrals of settlement-service business, while still allowing compensation for real services and cooperative arrangements between agents and brokers. If an agent steers you toward a provider, ask why.
Note also that seller credits are not a free-for-all. In Maine, for instance, seller credits cannot fund certain closing arrangements, so ask your agent how any credit you negotiate must be structured.
Perspective: what we tell first-time buyers
We have worked in central and southern Maine real estate for 20 years, and the pattern is consistent. First-time buyers rarely need more listings. They need someone who will explain the process without pressure and answer the phone when a question comes up at 7 p.m.
That is how we work. We use data, comparative market analyses and recent local sales to set a price range and decide how to negotiate, rather than relying on gut feel. We explain FHA and conventional financing options in plain language so you know what each means for your monthly payment. We also review condo and townhouse documents with buyers, because those packets hide costs like fees and rules that matter more than the paint color. If you are looking at an association property, our guide to HOA fees in Maine shows what to check.
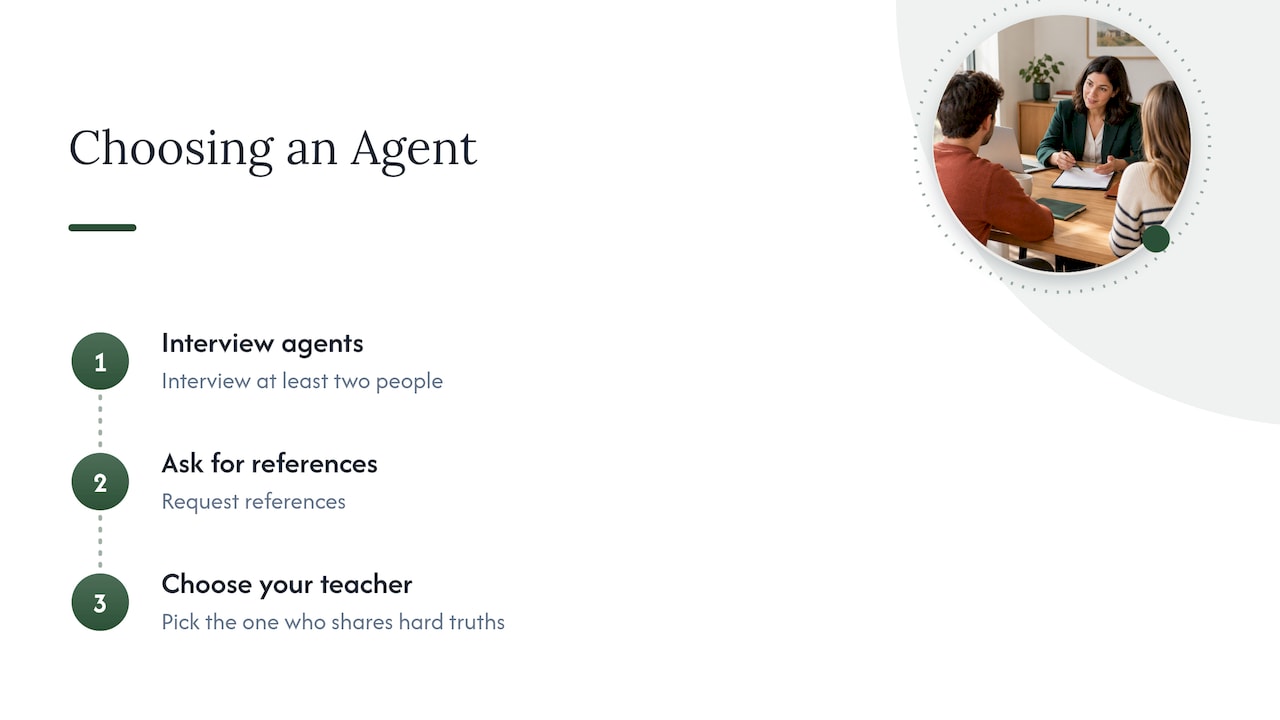
Our advice on choosing an agent, ours included: interview at least two people, ask for references and pick the one who tells you something you did not want to hear but needed to know. The right agent is a good teacher, not a closer.
— David
Work with a Maine agent who teaches as he goes
If you are buying your first home in central or southern Maine, we can start with a no-pressure conversation about your budget, timeline and the towns on your list. We help buyers search, price offers, negotiate and navigate inspections and closing, and we are reachable beyond standard business hours. See how we work on our buying and selling services page and reach out when you are ready to compare agents.
Before you talk, it helps to read our guide on qualifying as a first-time homebuyer in Maine, and, if you are weighing a newly built house, the notes on new construction versus resale.
Red flags when choosing an agent
- Pressure to sign immediately. A good agent gives you time to read the agreement and ask questions.
- Vague compensation language. If the fee is open-ended or described as a range, ask for a defined number.
- No references. Everyone has satisfied clients. If an agent cannot produce a name, ask why.
- Little local knowledge. If they cannot speak to the specifics of your target town, keep interviewing.
- Slow answers during the interview. Response times rarely improve after you sign.
- Steering to a single inspector or lender with no alternatives. A short list is fine. A single option with no explanation is not. Our guide to vetting Maine home inspectors gives you questions to check any name you are handed.
FAQ
How many agents should I interview before choosing one?
Two or three is a sound minimum. Fannie Mae advises speaking with several agents rather than feeling obligated to choose the first one. Use the same questions with each so you can compare their answers fairly.
Do I have to sign a contract with a buyer’s agent?
Generally yes, before you tour homes with the agent. HUD’s 2024 report says a written buyer agreement is required before visiting a property and that all of its terms are negotiable. Read the length, services, compensation and exit terms first, and ask a real estate attorney if anything is unclear.
Who pays my realtor?
That depends on your agreement. Compensation can be a flat fee, a percentage or an hourly fee, and a seller may pay it if you ask for that in your offer. If the seller does not pay, you may owe the amount in your agreement, so confirm it before touring.
Should I choose an agent who only works with first-time buyers?
Not necessarily. What matters is recent experience with buyers in your situation, your price range and your target area. An agent who handles a mix of buyers and sellers can still be an excellent choice if they can show relevant recent results and references.
When is the right time to call an agent?
Before you start touring homes and ideally around the time you are getting pre-approved. An early conversation lets you set a realistic budget and timeline and fix any credit or savings issues before they cost you an offer.
Sources
- Working with a Buyers Agent, Connecticut Department of Consumer Protection
- First Time Home Buyers, California Department of Real Estate
- Find the right home, Consumer Financial Protection Bureau
- Consumer Guide: Ten Questions to Ask a Buyer’s Agent, NAR
- Consumer Guide to Written Buyer Agreements, NAR
- Consumer Guide: Agency and Non-Agency Relationships, NAR
- HUD Housing Counseling Federal Advisory Committee sub-committee report, 2024
- What to ask your real estate agent, Fannie Mae
- 12 CFR 1024.14 Prohibition against kickbacks and unearned fees, CFPB