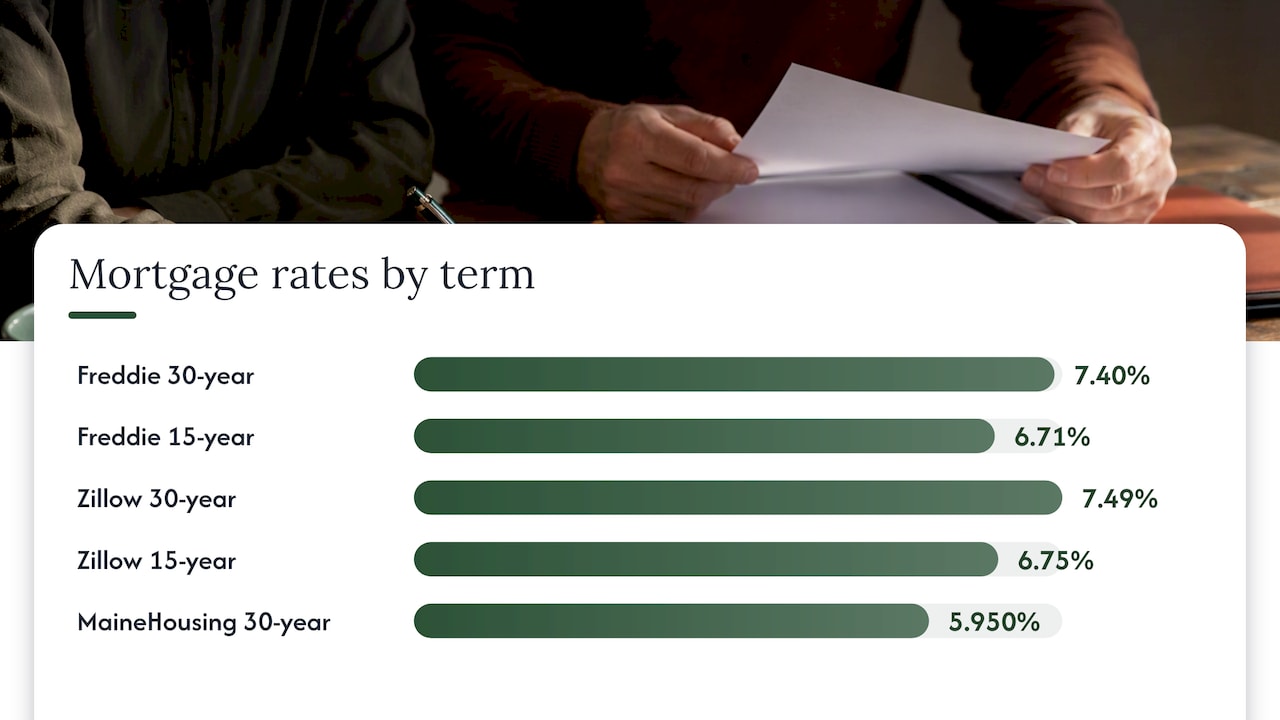
Maine mortgage rates are sitting in the mid-7% range for a standard 30-year fixed loan, and forecasters do not expect a quick drop. Freddie Mac’s national average was 7.40% on October 15, 2026, and Zillow’s Maine figure was 7.49% on October 19. The one clearly lower option for eligible buyers is a state-backed MaineHousing loan, which starts at 5.950%. Below, we walk through the numbers, what is driving them, what they mean for a monthly payment, and how to plan around them.
TL;DR
- The 30-year fixed rate in Maine is about 7.4% to 7.5% as of mid-to-late October 2026, depending on the source and the day.
- The Mortgage Bankers Association and Fannie Mae both expect rates to stay roughly in the 7.0% to 7.5% range through the rest of 2026 and into early 2027.
- MaineHousing’s First Home Loan is posted at 5.950% with zero points, and its First Generation program at 4.950%, if you qualify.
- Your own rate depends on credit, down payment and loan program, so a national average is a starting point, not a quote.
- Waiting for lower rates is a gamble. Plan the purchase around a payment you can carry today.
Table of Contents
- Where Maine mortgage rates stand right now
- The longer trend: a long stretch of high rates
- What forecasters expect through early 2027
- What a rate change does to your budget
- Why your rate won’t match the headline
- The MaineHousing option for first-time buyers
- Our perspective: plan for the payment, not the headline
- A simple plan for buyers in a high-rate market
- Working with us
- FAQ
- Sources
Where Maine mortgage rates stand right now
There is no single Maine rate. Every site that publishes one uses a different sample of lenders, a different borrower profile and a different day. That is why you will see numbers that disagree by a quarter point or more.
Here are the figures we can tie to a published source this month:
| Measure | 30-year fixed | 15-year fixed | Date |
|---|---|---|---|
| Freddie Mac national average | 7.40% | 6.71% | Oct 15, 2026 |
| Zillow Home Loans, Maine | 7.49% | 6.75% | Oct 19, 2026 |
| MaineHousing First Home Loan, 0 points | 5.950% | n/a | Effective Oct 1, 2026 |
Sources: Freddie Mac weekly survey archive, Zillow Home Loans, MaineHousing current interest rates.
Two things stand out. First, Maine’s market rate is running only slightly above the national survey, so you are not paying a big local penalty. Second, the MaineHousing rate sits roughly a point and a half below the market, which is a bigger gap than almost any other lever a buyer has.
Freddie Mac’s survey is built from loan applications submitted through its automated underwriting system by lenders nationwide, so it is a good gauge of direction. A quote from a lender is what you actually pay.
The longer trend: a long stretch of high rates
Maine buyers have lived with elevated rates for a while. MaineHousing’s 2026 housing outlook report notes that market rates have largely stayed in the 6% to 7% range since late 2022. October’s readings sit at or just above the top of that band.
The same report identifies mortgage rates as the dominant factor shaping Maine’s housing market, and it describes a lock-in effect. Homeowners who hold a lower-rate loan are reluctant to sell and take on a new, more expensive one. That keeps listings scarce, and scarce listings mean more competition for the homes that do come up.
That is the unusual part of this cycle for Maine: high rates have not produced an empty market. They have produced a tight one, where buyers face both a high payment and limited choice. If you are looking at a place like Portland, our look at the Portland, Maine housing market shows how wide the price range is even within one city.
What forecasters expect through early 2027
Two major forecasters published their October 2026 outlooks, and they land in similar territory.
- The Mortgage Bankers Association forecast projects a 30-year rate of 7.3% for the fourth quarter of 2026.
- The Fannie Mae housing forecast projects 7.4% to 7.5% for the same quarter.
Taken together, the expectation is a rate that stays in a 7.0% to 7.5% band through the end of the year and into early 2027, reflecting ongoing economic uncertainty. Forecasts are estimates, not promises, and they have been wrong in both directions before. But the practical message is consistent: do not build a purchase plan that only works at 5% or 6%.
What a rate change does to your budget
Rate moves feel abstract until you turn them into a monthly payment. MaineHousing’s outlook report offers a useful rule of thumb: with a $2,000 monthly payment cap, a 1% drop in interest rates adds about $20,000 to the home price a household can afford.
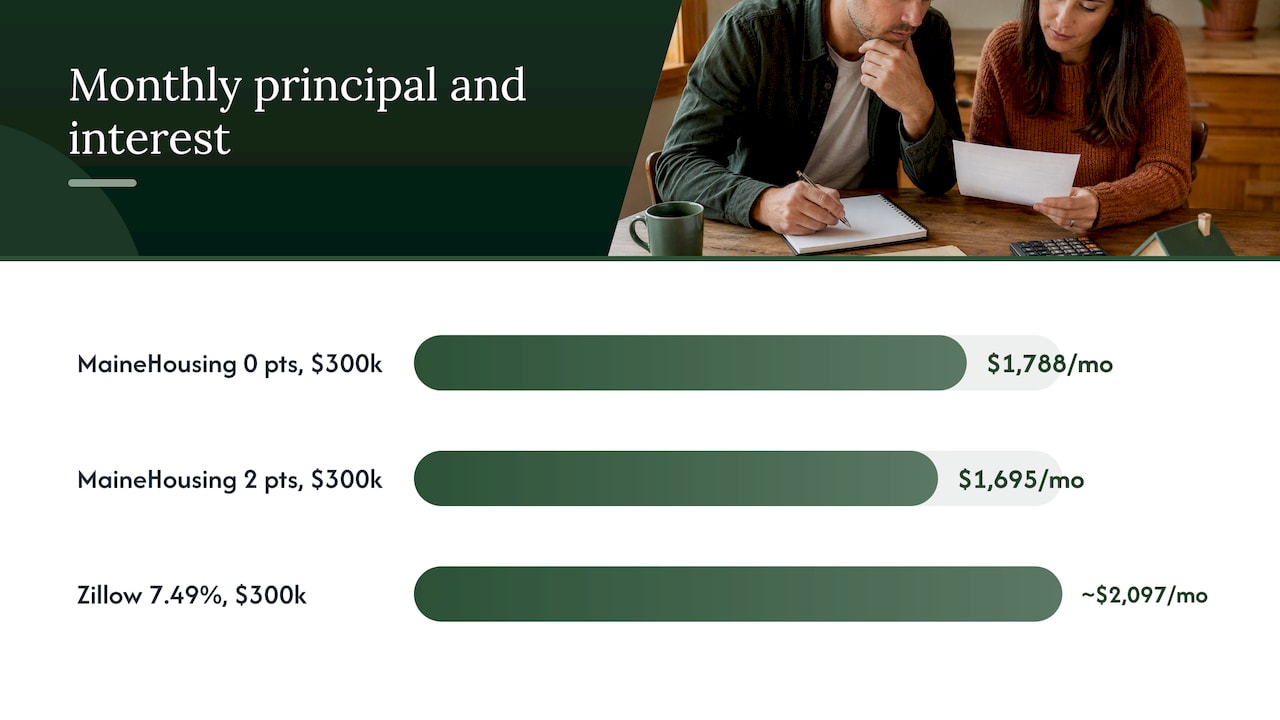
Here is a worked comparison using MaineHousing’s own payment factors. The agency publishes a monthly payment factor, which is the principal and interest per $1,000 borrowed. Multiply it by the number of thousands in your loan.
| Loan of $300,000 | Factor per $1,000 | Principal and interest per month |
|---|---|---|
| First Home Loan, 0 points (5.950%) | $5.96 | $1,788 |
| First Home Loan, 2 points (5.450%) | $5.65 | $1,695 |
Those factors come from the MaineHousing rate sheet. Taxes and insurance are extra, and the agency notes that your actual payment will be higher once they are escrowed.
For comparison, our own standard amortization math at 7.49% gives a factor of about $6.99 per $1,000, or roughly $2,097 a month on the same $300,000. That is an illustration of the Zillow-quoted rate, not a quote, and the gap against the 0-point MaineHousing payment is about $300 a month.
Why your rate won’t match the headline
The average is not your rate. Freddie Mac explains that lenders set individual rates based on credit risk, the loan program and the size of your down payment, so two neighbors can get very different offers on the same day.
That has a few practical consequences:
- Check your credit before you shop. A stronger profile moves you toward the better end of any published range.
- Compare the same loan. A 30-year fixed with points is not comparable to a 30-year fixed without. Ask for the rate, the points and the APR together.
- Compare programs, not just lenders. FHA, conventional, VA, USDA and MaineHousing loans price differently. If you are a veteran, see our guide to buying in Maine with a VA loan. If you are looking at rural areas, read about the two checks that decide USDA loans.
- Get preapproved. It shows you your real rate range and what sellers look for. Our Maine preapproval playbook covers it.
The MaineHousing option for first-time buyers
For many Mainers, the most important rate trend is not the national one. MaineHousing’s October 1, 2026 rate sheet lists the First Home Loan at 5.950% with zero points, with an APR of 6.495%. Its First Generation program, for borrowers who have never lived in a home owned by their biological parents or legal guardians, is listed at 4.950% with zero points.
Maine analysts quoted in the outlook report point out that these state-backed programs tend to hold lower rates even when national rates are volatile, which gives first-time buyers a path in when the market is expensive. Programs have income and purchase-price limits, so confirm your eligibility with a participating lender. Our guide to the first-time homebuyer path in Maine explains how to qualify.
Points or no points
MaineHousing offers both a zero-point and a low-point structure. Paying points upfront, typically 1% to 2% of the loan, lowers the rate and the payment, as the table above shows. But the MaineHousing FAQ notes that cash for closing costs is often the main barrier for local buyers, so many first-time buyers are better served by the zero-point option.
The tradeoff is simple. Points pay back over time, so they make sense if you will stay for years. If cash is tight now, keeping it is usually wiser. We break down the math in points versus no points for Maine homebuyers.
When the rate is actually locked
A common mistake: assuming your rate is fixed when you apply. For MaineHousing loans, the rate is locked only when the lender reserves the loan with MaineHousing, and that can happen only after a purchase and sale agreement is fully executed. Until then, you are exposed to the posted rate on the day of reservation. Ask your lender exactly when and how your lock happens, and what it costs to extend if closing slips.
Our perspective: plan for the payment, not the headline
After 20 years in the Maine market, we have watched buyers wait for the perfect rate more often than we have seen them get it. Our view is practical.
First, a rate is only one input. Price, taxes, insurance, inspection findings and appraisal outcomes move your total cost as much as a quarter point does. If an appraisal comes in low, for example, there are options before you cover the gap, which we cover in our piece on requesting a reconsideration of value.
Second, you can refinance if rates fall, but you cannot undo a home you were priced out of or one you overpaid for. That is why we put so much effort into pricing. Sellers should read our take on why a headline number is only a starting point when pricing a Maine home, and buyers should treat comparable sales the same way.
Third, work backward from your budget. Decide on the payment you can carry comfortably, then see which towns and homes fit. Our look at what a typical Maine income buys across regions is a good place to start.
Finally, we answer the phone outside standard hours, because rate changes and offers do not follow a nine-to-five schedule. We give advice without pressure, and sometimes that advice is to wait or to look at a different town.
— David
A simple plan for buyers in a high-rate market
- Set your payment ceiling first. Use total monthly cost, including taxes and insurance, not just principal and interest.
- Get preapproved with two or three lenders. Include one that offers MaineHousing loans if you are a first-time buyer.
- Choose your points strategy. Keep cash if closing costs are your limit. Buy down only if you plan to stay long enough to recoup it.
- Ask about the lock. Know the date, the term and the extension cost before you write an offer.
- Expect competition. With owners holding onto low-rate loans, listings stay scarce. Be ready to move quickly on a well-priced home.
- Revisit refinancing later. If rates fall meaningfully, run the numbers on closing costs against monthly savings.
Sellers have their own planning to do. Buyers with high payments are sensitive to price, so a correct list price matters more than ever, and a good listing strategy leans on comparable sales rather than hope.
Working with us
We are a licensed REALTOR® practice serving buyers and sellers across central and southern Maine, including first-time buyers, relocating families, investors, seniors downsizing, and people looking for vacation or seasonal property. We help with home search, pricing, negotiation and comparative market analyses, and we can walk you through FHA and conventional financing basics before you talk to a lender. To talk through your situation, visit RealtorMaine.
FAQ
Are mortgage rates trending up or down right now?
On the figures we can verify, rates are holding in the mid-7% range. Freddie Mac’s 30-year average was 7.40% on October 15, 2026, and the 15-year average was 6.71%, slightly lower than the previous week’s 6.73%. That is a plateau with small weekly moves, not a clear trend.
Will mortgage rates go down to 5%?
Nothing in the October 2026 forecasts from the Mortgage Bankers Association or Fannie Mae points that way. Both expect the 30-year rate to remain around 7.0% to 7.5% into early 2027. A 5% market rate would require a large shift, so do not rely on it for your plan.
Can I get a rate below the market average in Maine?
Possibly, through MaineHousing. As of October 1, 2026, its First Home Loan is posted at 5.950% with zero points, and its First Generation program at 4.950%. You must meet program rules on eligibility, income and price, so check with a participating lender.
Should I wait for rates to fall before buying?
It depends on your budget and timeline. If you can comfortably afford today’s payment, buying now and refinancing later is an option. Maine inventory is tight, and a lower rate could bring more buyers back into competition, so waiting does not guarantee a better deal.
Sources
- Freddie Mac, Primary Mortgage Market Survey
- Freddie Mac, weekly survey archive
- Freddie Mac, mortgage rates and affordability
- Zillow Home Loans, Maine mortgage rates
- MaineHousing, current interest rates
- MaineHousing, First Home Program FAQs
- MaineHousing, First Generation Program
- MaineHousing, 2026 Maine’s Housing Outlook Report
- Mortgage Bankers Association, Mortgage Finance Forecast, October 2026
- Fannie Mae, Housing Forecast, October 2026