Most Maine home purchases close about 30 to 45 days after the offer is accepted. Coastal, seasonal or title-complicated properties can stretch to 45 to 60 days, and a cash purchase can be much faster. One note on vocabulary: Maine buyers rarely say “escrow” the way Californians do. Your deposit sits in a broker’s trust account or an attorney’s escrow account, and the closing is handled by a Maine attorney or a registered settlement agency. The clock still runs the same way, from accepted offer to deed and keys.
Below is the stage-by-stage timeline, the dates that matter, and what you can do to keep your closing on schedule.
TL;DR
- Plan on roughly 30 to 45 days from a signed purchase and sale agreement to closing, and 45 to 60 days for coastal, seasonal or complicated-title homes.
- Earnest money is typically due within 3 to 5 business days of acceptance, and a broker holding it as trustee must deposit it within 5 business days.
- The longest stretch is financing: appraisal and underwriting run in parallel with title work, and your response time to the lender is the biggest factor you control.
- You get the Closing Disclosure three days before closing and can request a walk-through about 24 hours before.
- Book inspections the day your offer is accepted, because the inspection window is short.
Table of Contents
- How Long Does a Maine Closing Take?
- The Maine Closing Timeline, Stage by Stage
- The Milestones to Put on Your Calendar
- Earnest Money: When It Is Due and Who Holds It
- Inspections: The Shortest Clock in the Process
- Appraisal, Underwriting and Title: The Parallel Tracks
- What Can Delay a Maine Closing
- The Final Week and Closing Day
- A Week-by-Week View for a 45-Day Closing
- Our Perspective
- Working With a Maine Realtor Through Closing
- FAQ
- Sources
How Long Does a Maine Closing Take?
The figure you will see most often is 30 to 45 days from executed contract to closing. A Maine lender’s guide to the mortgage process puts it at 30 to 45 days in Maine and New Hampshire, stretching toward 45 or 60 days when an appraisal hits a snag, the title history is complicated, or the borrower is slow returning documents. A guide to the Maine purchase and sale agreement says coastal and seasonal properties often run 45 to 60 days.
The date that actually binds you is the one written in your contract. The purchase and sale agreement sets a closing date, and a bank involved typically needs six to eight weeks or so to finish. If your contract date is tighter than your lender can realistically meet, ask for a realistic date before you sign, not after.
| Buyer type | Typical time from acceptance to closing |
|---|---|
| Financed purchase, standard property | About 30 to 45 days |
| Financed, coastal or seasonal, or title issues | About 45 to 60 days |
| Cash purchase | Often 7 to 14 days, since no lender is involved |
The Maine Closing Timeline, Stage by Stage
A Maine transaction timeline from a transaction-coordination platform breaks the process into four phases. Treat these as typical ranges, not promises. Your contract and your lender set the real dates.
Pre-contract: about 7 to 14 days
This is the search, showings and getting your financing ready. A strong preapproval matters here, because sellers and state programs look at it closely. Our Maine preapproval playbook covers what they check.
Contract: about 3 to 7 days
Once the offer is accepted and the purchase and sale agreement is signed, several things start at once:
- Earnest money is delivered.
- Inspections are scheduled.
- The mortgage application is formally submitted.
- Title work is ordered or queued, depending on your attorney’s practice.
Due diligence: about 21 to 35 days
This is the long middle. Inspections, appraisal, title review and underwriting all happen here. If the property has a well, septic system or shoreline, expect extra steps.
Closing: about 5 to 7 days
The last week covers the final walk-through, document preparation, payment of transfer tax, deed recording and the handoff of keys.
The Milestones to Put on Your Calendar
The same Maine timeline source lists these as typical benchmarks. Your contract’s dates override all of them.
| Milestone | Typical timing after acceptance |
|---|---|
| Earnest money delivered | 3 to 5 days |
| Home inspection completed | 10 to 14 days |
| Title commitment | About 21 days |
| Loan commitment | 21 to 30 days |
| Final walk-through | 24 to 48 hours before closing |
| Closing Disclosure | 3 days before closing |
Earnest Money: When It Is Due and Who Holds It
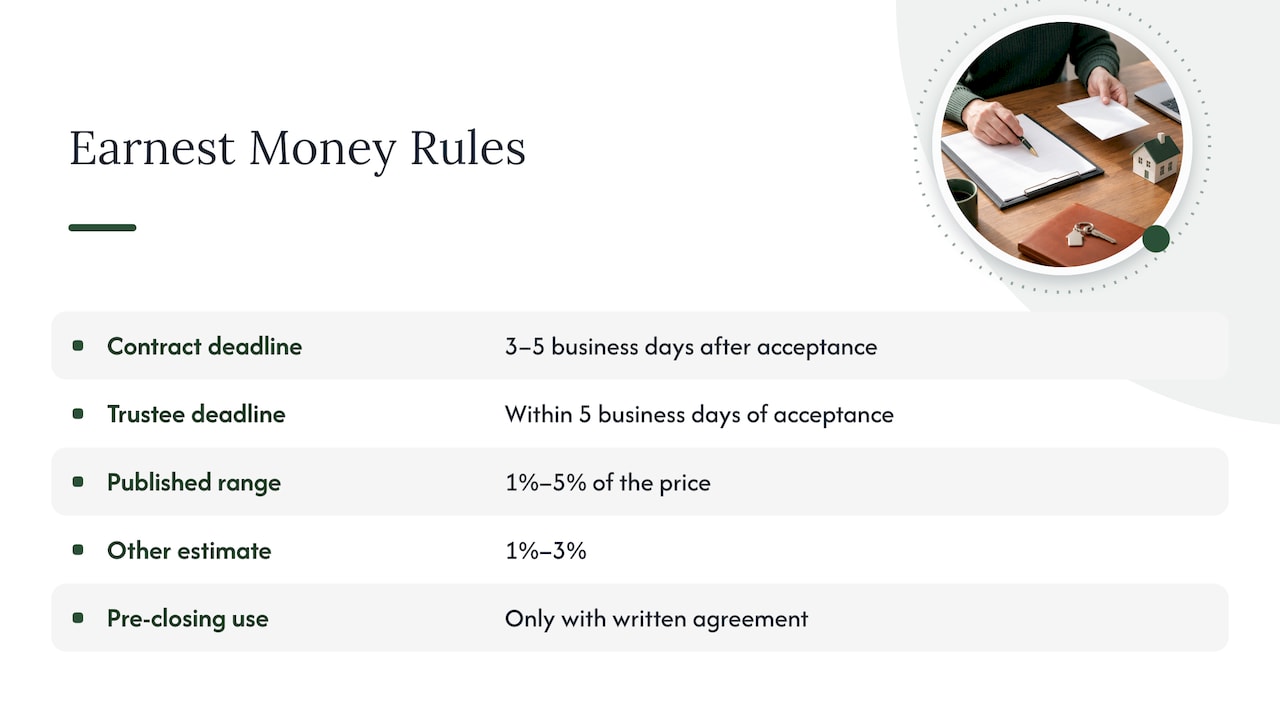
Most Maine contracts call for the deposit within 3 to 5 business days of acceptance. Under the Maine Real Estate Commission’s trust account rule, a designated broker holding a deposit as trustee must deposit it within 5 business days of acceptance. The same rule bars mixing the deposit with the brokerage’s own money, and it limits using the deposit for pre-closing expenses unless everyone agrees in writing.
How much? Published guidance varies. One guide says Maine deposits typically run 1% to 5% of the price, with lower figures in slower rural markets and higher ones in competitive coastal markets such as Portland, Bar Harbor and Kennebunkport, per the purchase and sale guide. Another source says 1% to 3%. Your agent can tell you what is realistic for the town and price point you are shopping.
If a deal falls apart and both sides claim the deposit, the Real Estate Commission’s consumer FAQ explains that the broker as trustee must follow the disputed-deposit procedures in Chapter 400. The Commission itself does not decide who gets the money. The practical lesson is to read your contingency deadlines closely, because they decide whether your deposit is protected.
Inspections: The Shortest Clock in the Process
The inspection window is where buyers most often lose time. Ten to 14 days is a common benchmark, and good inspectors book up quickly, especially in summer. Call one the day your offer is accepted.
Two of our guides cover this stage:
- Maine inspection contingencies explains why you should book fast and act within 7 to 14 days.
- The home inspection checklist for Maine buyers shows what to look at in older New England homes.
If the home was built before 1978, lead paint rules add their own rights and deadlines. See our guide to Maine lead paint rules for transactions. Sellers also owe disclosures, and our seller disclosure guide maps them to Title 33.
Appraisal, Underwriting and Title: The Parallel Tracks
The reason a Maine closing feels unpredictable is that it is not one line. The Maine lender guide describes several tracks running at once: application, appraisal, underwriting and title search. When one stalls, it can hold up the others.
Appraisal
For MaineHousing loans, the lender must obtain an appraisal from a licensed appraiser, and the home must be suitable for year-round occupancy with no more than 15% commercial use, per the MaineHousing Home Mortgage Procedural Guide. That matters if you are eyeing a seasonal camp or a property with a business component.
Underwriting
The underwriter reviews income, credit, the property and the appraisal against the loan program’s rules. According to the same lender guide, how fast you answer underwriter conditions is one of the biggest things in your control. Answer within a day, and keep your finances quiet: no new credit, no job changes, no large unexplained deposits.
One source puts mortgage approval at 20 to 30 days, the largest gap in the whole timeline.
Title
Maine closings are attorney-driven. According to the purchase and sale guide, Maine is an attorney-mandatory state where a licensed attorney supervises the closing, including title examination and deed drafting. Another source notes that Maine does not require a lawyer to sell a house, and that closings may be run by a registered settlement agency or a Maine attorney. Ask your agent which applies to your closing.
Attorney practices differ. One Maine firm explains that it waits for a loan commitment before starting title work, to spare the client the expense if financing falls through. If your closing attorney works that way, the title tail comes late in your timeline, so ask early. For what title coverage costs and who pays, read our Maine title insurance guide.
What Can Delay a Maine Closing
Common delays, per a general escrow timeline overview, are underwriting conditions, low appraisals, repair negotiations after inspection, title defects, document errors and scheduling conflicts. In Maine, a few local factors add to the list:
- Coastal and shoreland properties. Flood zone determinations, septic inspections and shoreland zoning checks add review steps.
- Summer demand. In vacation markets such as Bar Harbor, Kennebunkport and Boothbay Harbor, May through August tightens attorney availability, according to the same guide.
- Condos and townhouses. Association documents take time to assemble. See our guide to Maine condo documents and the 10-day resale certificate rule, and for FHA buyers, FHA condo approval in Maine.
- Tenant-occupied homes. Deposits and tenancy rights need handling before closing. See Maine property with tenants.
- Rate lock expiry. A slow response to your lender can cause your lock to expire, which may mean a higher rate or an extension fee.
The Final Week and Closing Day
MaineHousing’s steps to homeownership describes the end of the process. Three days before loan closing, you can review the Closing Disclosure, which gives your final loan terms, projected monthly payment, and fees and closing costs. You can request a walk-through about 24 hours before closing to confirm the seller has moved out and left the home in acceptable condition, with included appliances and negotiated items.
Use the walk-through to confirm each agreed repair is complete. Run the water, flush toilets, check under sinks and look at drains. If a repair involved plumbing, it helps to know what inspecting plumbing before closing can uncover, such as sewer line problems that are expensive once you own the house.
On closing day you sign the loan and transfer documents and pay your closing costs, escrow items and down payment. The seller receives payment, and you receive the deed and keys. Not sure what to budget? Our guide to Maine closing costs for buyers and sellers walks through the numbers, including the real estate transfer tax split.
A Week-by-Week View for a 45-Day Closing
Here is how a typical financed purchase might play out. Your own contract will differ.
- Days 1 to 3: sign the purchase and sale agreement, deliver earnest money, book the inspector, send your application documents to the lender.
- Days 4 to 14: inspection and any specialty tests (well, septic, radon, as relevant). Negotiate repairs or credits within your contingency window.
- Days 10 to 21: appraisal ordered and completed. Title work begins or continues.
- Days 21 to 35: underwriting conditions, loan commitment, homeowner’s insurance in place.
- Days 35 to 42: Closing Disclosure arrives, wire or certified funds arranged, final questions to your attorney.
- Days 43 to 45: walk-through, signing, recording, keys.
Our Perspective
We have helped central and southern Maine buyers and sellers through closings for 20 years, and the pattern is consistent: the deals that close on time are the ones where everyone knew the calendar on day one.
That is why we lay out every deadline in plain language the day your offer is accepted: when the deposit is due, when the inspection window closes, when the lender needs documents and when the walk-through happens. Closings are stressful enough without surprises, and we make ourselves available beyond standard hours because lenders and attorneys do not only email between nine and five.
We also tailor the plan to the property. A first-time buyer financing with FHA, a family relocating to central Maine, a retiree downsizing from a larger home and a buyer chasing a coastal camp all face different clocks. We use data and local knowledge to set a realistic closing date, so the contract reflects how long the process will really take.
Our approach is transparent and pressure-free. If a date needs to move, you hear it from us early, with options.
David
Working With a Maine Realtor Through Closing
If you are buying or selling in central or southern Maine, we can walk you through the timeline for your specific property, from pricing and negotiation to the final signing. We work with buyers, sellers, investors and vacation property seekers, including FHA and conventional financing and condo or townhouse document review.
Start on the RealtorMaine home page to reach us about buying a home, selling your home, investment property or a vacation or seasonal property.
FAQ
Is there really “escrow” in Maine?
The word is used loosely. Your earnest money is held in a broker trust account or an attorney’s escrow account, and the closing is handled by an attorney or registered settlement agency. Lenders may also set up an escrow account for taxes and insurance after closing. The timeline you care about is acceptance to closing.
Can I close faster than 30 days?
Sometimes. Cash buyers often close in 7 to 14 days, since no lender is involved. Financed buyers can close faster if the appraisal, title work and underwriting go smoothly and the contract date allows it, though lenders commonly need several weeks.
When is my earnest money due?
Usually within 3 to 5 business days of acceptance, per your contract. A broker acting as trustee must deposit it within 5 business days of acceptance under Maine Real Estate Commission rules. Confirm the exact deadline in your signed agreement and deliver on time.
How much notice do I get before closing?
You receive the Closing Disclosure three days before loan closing, and you can request a walk-through about 24 hours ahead, as MaineHousing explains. Use that window to review fees and confirm agreed repairs.
What is the best way to avoid delays?
Book inspections immediately, respond to lender requests within a day, and keep your finances unchanged until closing. Regular check-ins with your lender, attorney and agent help keep contingencies moving.
Sources
- Maine transaction timeline (ListedKit)
- Maine Purchase and Sale Agreement guide (Quill)
- Modern mortgage process in Maine (CUSO Home Lending)
- Maine Real Estate Commission consumer FAQ
- 02-039 C.M.R. ch. 400, § 2, Real Estate Trust Accounts
- MaineHousing Home Mortgage Procedural Guide
- MaineHousing Steps to Homeownership
- Understanding average timelines for Maine closings (Generis)
- How Long Does Escrow Last (Legal Clarity)
- How to Sell a House by Owner in Maine
- Real Estate Transactions in Maine (Shepard and Read)
- Inspect plumbing before closing